


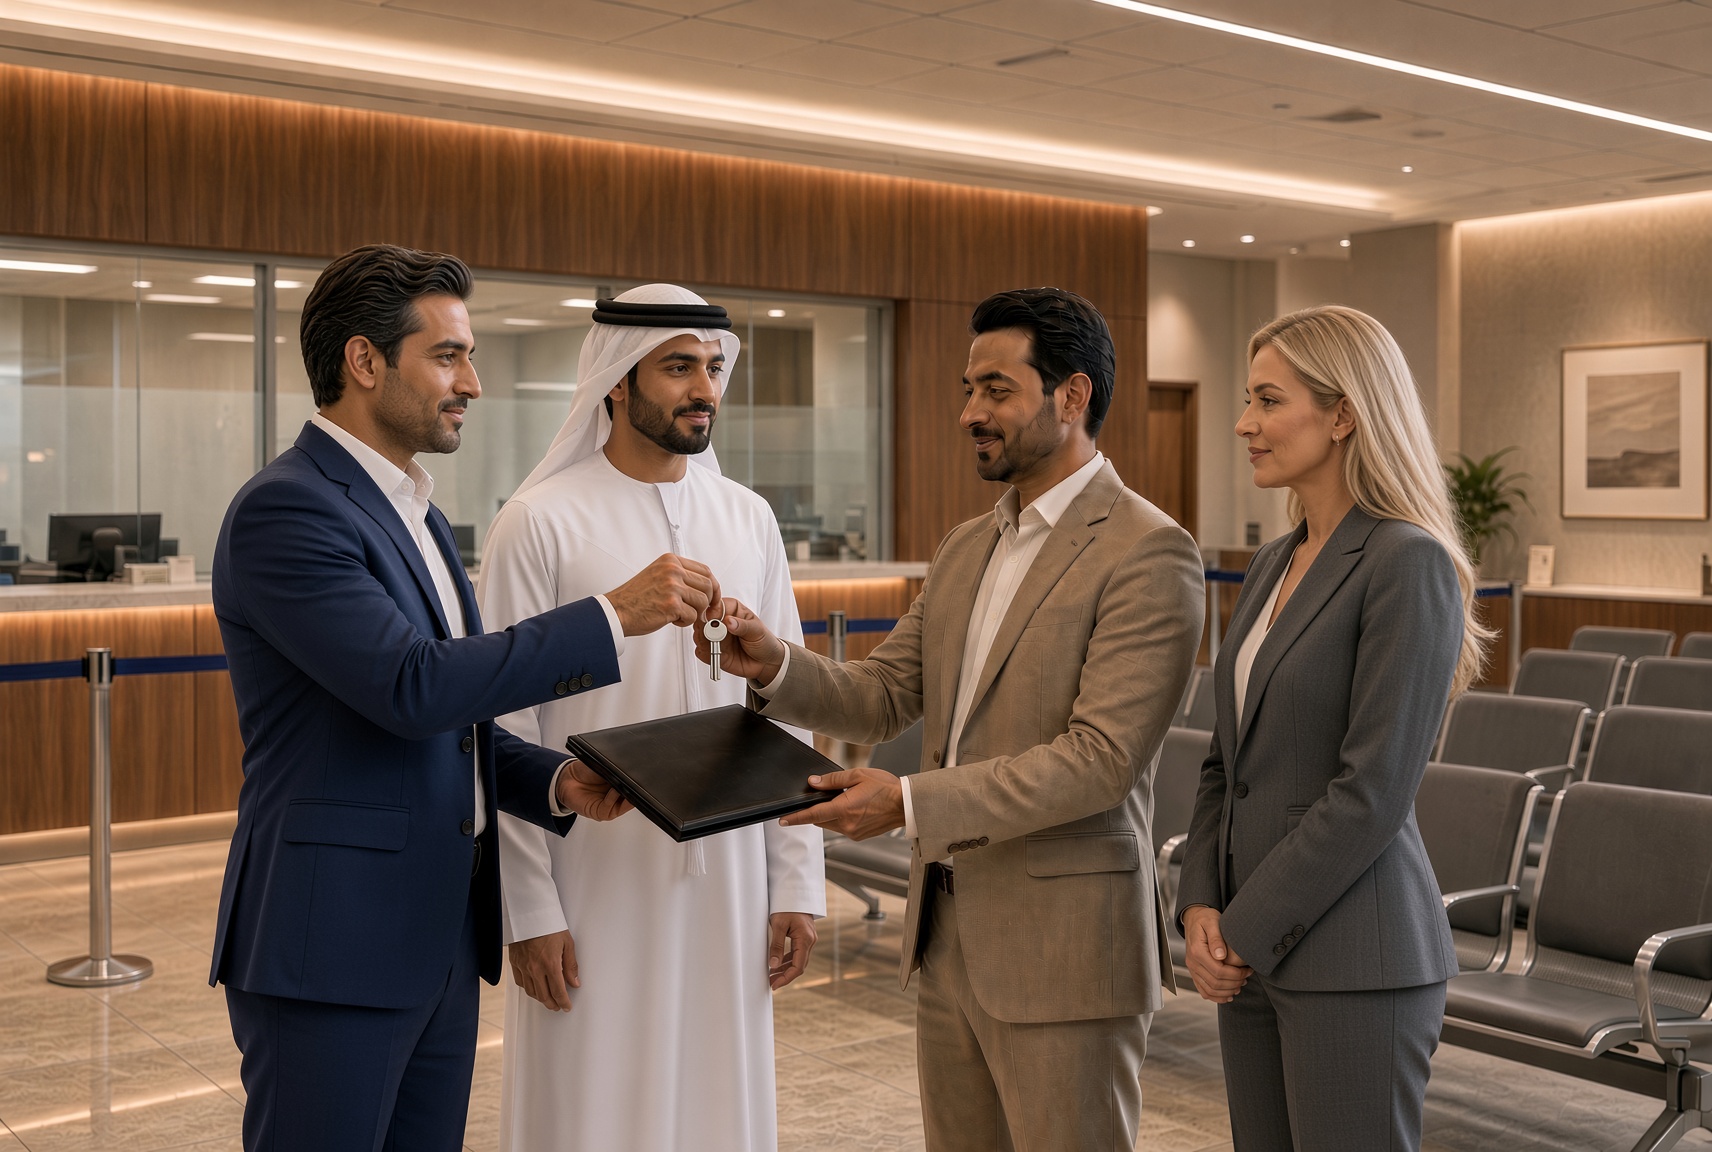


After weeks of talks, viewings and paperwork, it all comes down to one day: transfer day. It's the day the business officially moves from the seller to the buyer.
For many first-time buyers and sellers, this is the part that feels most uncertain. Who pays whom, and when? What gets signed? What happens to the keys, the staff and the accounts?
Here's how transfer day usually works in a Dubai business sale, and what to get ready beforehand.
Before Transfer Day: What Must Be Done First
A smooth transfer day depends on the work done before it. By the time you get there, these should already be in place:
- Agreed price and terms: the price, what's included and the payment steps, all set out in a signed sale agreement.
- Deposit paid: the buyer pays a deposit to secure the deal. With BFS, we hold this deposit, not the seller.
- Due diligence done: the buyer has reviewed the financials, bank statements, lease, licence and any contracts.
- Landlord approval: the landlord has agreed in writing to the change of owner or the lease transfer.
- Approvals for regulated businesses: clinics, nurseries, pharmacies and similar businesses may need approval from the relevant authority before the change of ownership.
- Bills cleared: outstanding rent, DEWA, service charges, supplier bills and fines are settled or agreed in writing.
- Staff position agreed: it's clear which staff are staying, and how visas and end-of-service benefits will be handled.
If any of these are still open, transfer day is usually pushed back. That's normal, and it's better than rushing.
On Transfer Day: Step by Step
1. Final check
Both sides confirm that everything agreed is ready: documents, approvals and the list of what's included in the sale.
2. The buyer pays the balance
The buyer pays the rest of the price, after the deposit, directly to the seller. This is usually done by manager's cheque or bank transfer. The payment is made before the licence is transferred, so the seller is protected.
3. Security deposit and advance rent
If the seller has paid a security deposit to the landlord or rent in advance, this money goes back to the seller, on top of the sale price. It should already be agreed in the sale agreement, so there are no surprises on the day.
4. Broker commission is settled
Once the seller has received the funds, the broker's commission is paid before the transfer goes ahead.
5. The ownership and licence transfer
The parties sign the documents to change ownership, and the trade licence is updated to show the new owner. For mainland companies this goes through the Department of Economy and Tourism (DET, formerly DED). Some changes may also need a notary. Free zone companies follow their own free zone's process.
6. Handover
Once the transfer is done, the seller hands over the business:
- Keys, access cards and alarm codes
- Passwords for the POS, booking system, website, email and social media
- Supplier and customer contact lists
- Stock, counted and signed off
- Equipment, checked against the agreed list
- Company documents, stamps and any originals
After Transfer Day: What the New Owner Still Needs to Do
The deal is done, but a few things should follow quickly:
- Ejari and lease: register the lease in the new owner's name if needed.
- DEWA and utilities: move accounts into the new owner's name.
- Bank account: update signatories or open a new account for the business.
- Staff visas: transfer or renew staff visas under the new ownership where required.
- Suppliers and customers: let key suppliers and regular customers know about the change, if the new owner wants to.
- Handover period: many sales include a short period where the seller helps the buyer settle in. Agree this in writing.
Common Problems That Delay Transfer Day
- The landlord hasn't given written approval
- Unpaid bills or fines on the company
- Missing or expired documents, such as the Ejari or licence
- Authority approval still pending for regulated businesses
- Last-minute disagreement over what's included
Most delays can be avoided by sorting these out early.
How BFS Helps on Transfer Day
At BFS, we manage the deal from the first enquiry to the handover. We hold the buyer's deposit, coordinate the paperwork and approvals, and are there on transfer day to make sure both sides get what was agreed.
If you're thinking of buying or selling a business in Dubai, talk to us.
FAQ Section
What happens on business transfer day in Dubai?
The buyer pays the balance to the seller, the ownership and trade licence are transferred to the buyer, and the seller hands over the keys, accounts, stock and documents.
Who holds the deposit when buying a business through BFS?
BFS holds the buyer's deposit. The balance of the price is paid by the buyer directly to the seller on transfer day.
Is the payment made before or after the licence transfer?
The balance is paid before the licence transfer, so the seller has received the funds before ownership changes.
Who gets the landlord security deposit when a business is sold?
The security deposit and any rent paid in advance normally go back to the seller, on top of the sale price.
Where is a trade licence transferred in Dubai?
For mainland companies, through the Department of Economy and Tourism (DET, formerly DED). Free zone companies follow their free zone's own process.
What can delay transfer day?
The most common causes are missing landlord approval, unpaid bills or fines, missing documents, and pending approvals for regulated businesses such as clinics or nurseries.
Sharing Is Caring!